What is included
Chris tells you honestly whether the damage looks like enough for a claim before you call your insurer.
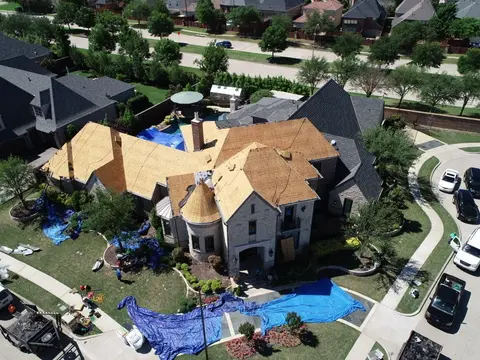
Dated photos of every damaged area give you a clear record of what the storm did.
You understand the options and likely scope before the claim is filed.
Chris meets your adjuster on the roof to show the damage he documented.
A line-item estimate of the work the documented damage requires.
We explain the steps, the paperwork and what the insurer's estimate means.
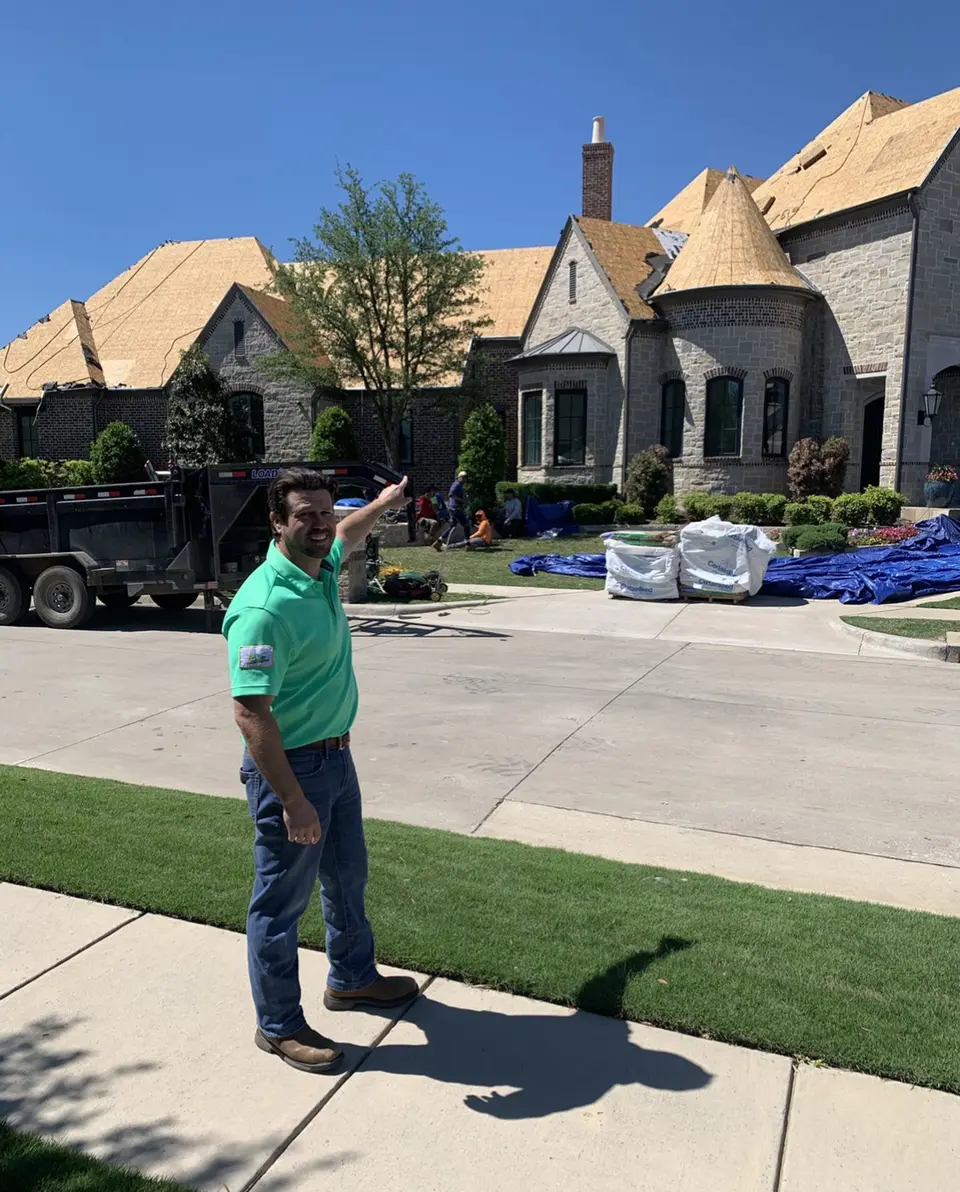
When the claim is settled, we complete the repair or replacement and clean up.
Who this is for
This page is for Dallas–Fort Worth homeowners and building owners who think a storm damaged their roof and want to understand the insurance side before they make a call. Most people file a roof claim rarely, and the process, the paperwork and the vocabulary can feel unfamiliar.
Verde Roofing's role is clear and limited by Texas law. The claim is yours. We inspect, document, meet your adjuster on site to show the damage we found, write the repair estimate, explain the process, and do the work.
What Texas law says about roofers and claims
Two Texas rules shape everything on this page:
- Roofers cannot act as your adjuster. Texas Insurance Code §4102.163 says a contractor may not act as a public adjuster or advertise to adjust claims on property it is working on or may work on. Only a licensed public adjuster may represent a policyholder in a claim. So Verde never says it will negotiate your claim, and you should be cautious of any contractor who does.
- Roofers cannot cover your deductible. A 2019 Texas law (House Bill 2102) made it illegal for a contractor to pay, waive, rebate or absorb an insured's deductible. The Texas Department of Insurance warns homeowners about these offers. Our guide on why no roofer can legally waive your deductible explains the details.
How the free inspection works
Before you call your insurer, Chris Grimes inspects the roof with you. He photographs the damage, checks gutters, vents and other soft metal for hail marks, and explains whether the damage looks like enough for a claim. If it is minor, or likely below your deductible, he tells you so and you can decide not to file. Read should you call a roofer or your insurance company first for the pros and cons.
The claim, step by step
| Step | Who does it |
|---|---|
| Report the claim and get a claim number | You |
| Inspect and photograph the damage | Verde, with you |
| Meet the adjuster on site | Your adjuster, with Chris there to show the damage |
| Decide what the policy pays | Your insurer, under your policy |
| Questions about the insurer's estimate | You, with Verde's photos and estimate to refer to |
| Repair or replacement | Verde |
Our full guide to how a roof insurance claim works in Texas goes deeper, and what to expect at the adjuster's inspection covers the visit itself. To build your own record, follow how to document roof storm damage.
What to have ready before the adjuster comes
A little preparation makes the adjuster's visit shorter and clearer:
- Your policy number, claim number and the date of the storm
- Your declarations page, so you know your deductible and whether the policy pays replacement cost or actual cash value
- Dated photos of hail on the ground, dents on gutters, vents and cars, and any interior leaks
- Receipts for emergency repairs such as tarping
- A list of other damage you noticed: fences, siding, window screens, outdoor equipment
- Verde's inspection photos, which Chris brings to the meeting
Write down the adjuster's name and contact details, and ask when you should expect the insurer's estimate.
Understanding the insurer's payment
Many policies pay in two parts: actual cash value first, then the held-back depreciation once the work is done. Some older-roof policies pay only actual cash value. Our guide to ACV vs. RCV and the second check explains the difference. If the insurer's estimate leaves out items found during the work, a supplement may be requested; see what a roof insurance supplement is.
What we do not do
We do not negotiate, settle or dispute your claim, we do not sign anything on your behalf with the insurer, and we do not cover your deductible. If your claim is denied and you want someone to represent you, a licensed public adjuster or an attorney can do that. Our guide to options after a denied roof claim lists them.
The work after the claim
Once the claim is settled, Verde completes the roof replacement or roof repair with Malarkey or Owens Corning shingles or the material your roof already uses, and storm-damaged gutters or siding where needed. See storm and hail damage for the full storm process.
Where we work
From Plano we help homeowners in Collin, Dallas, Denton, Tarrant, Rockwall, Ellis, Hunt, Kaufman, Johnson, Parker and Wise counties. See our service areas.
Start with a free inspection
Call or text (214) 687-1951, 24/7, or book a free inspection. Chris will show you what he finds before you decide anything.